The Tax on Patience: Why India Should Scrap Equity LTCG
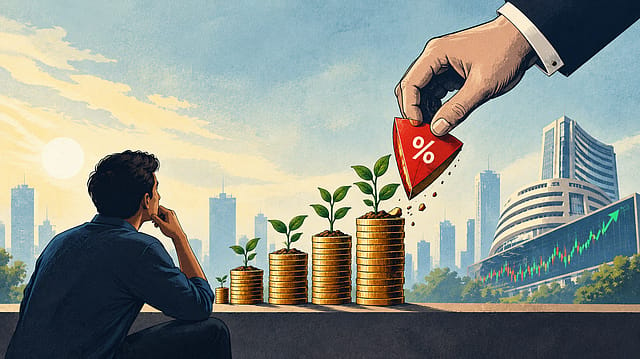
India wants its citizens to invest patiently. Yet when patience pays, the taxman takes a slice. That contradiction sits at the heart of the renewed debate over scrapping long-term capital gains tax on equities. The strongest case for abolition is not that investors deserve a rising market. It is that long-duration risk capital deserves a more coherent bargain.
Will the government oblige? There is no announced decision. In July, it told Parliament that abolition was not under consideration. But an October 26 report in The Indian Express says Budget 2027-28 discussions include reducing the 12.5 per cent LTCG rate for domestic and foreign investors. An official said “every option” was being discussed. A cut is therefore a live possibility; abolition remains a policy choice, not a promise.
Look Who's Talking Regime Change
23 Oct 2026 - Vol 05 | Issue 43
Currently, long-term gains on listed shares and equity-oriented mutual funds attract 12.5 per cent tax above an annual exemption of Rs 1.25 lakh. The exemption cushions smaller realised gains, but the levy still reduces what investors retain after taking market risk.
The argument for scrapping it should begin with patience, not prices. India needs investors willing to finance businesses through difficult cycles, rather than chase the next trading opportunity. Abolition could be tied to a longer qualifying holding period, making the concession a reward for staying invested rather than a subsidy for quick exits. SBI’s October 12 Ecowrap advocated precisely this direction: extend the holding period to two or three years and abolish equity LTCG tax.
For foreign investors, the friction extends beyond the headline rate. Rupee depreciation can erode dollar returns even when an investment shows a taxable rupee gain. The government is reportedly examining dollar-based computation alongside a rate reduction—a recognition that the tax base matters as much as the percentage applied to it.
Removing this friction would improve post-tax returns. It could also strengthen India’s proposition when global funds compare destinations. But that is an argument about competitiveness, not a guarantee of inflows—valuations, corporate earnings, currency movements and global interest rates remain decisive. A tax concession cannot manufacture an attractive investment.
Nor is abolition free. The government reported equity LTCG tax revenue of Rs 1,29,158 crore for assessment year 2025-26, relating to financial year 2024-25. Supporters cannot simply assume that faster growth would replace the money. Any proposal needs a credible fiscal offset and an honest assessment of who benefits.
That argues for targeted abolition, not indiscriminate generosity. Protect genuine long-term equity investment, retain taxation of shorter-term gains, and avoid special treatment available only to overseas money.
The political challenge is to explain why this is more than a favour to shareholders. The answer must lie in a stable bargain, which is longer commitment in exchange for a lighter tax burden. India should scrap equity LTCG for genuinely patient capital—not to rescue today’s index, but to make tomorrow’s investment decisions less hostage to tax friction. Until the Budget delivers, however, investors should distinguish a persuasive case from an enacted concession.