19 Years. ₹1.46 Lakh Crore in Revenue. Where’s the Profit, Flipkart?
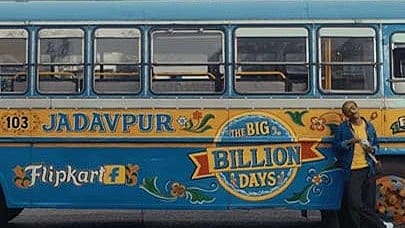
How old must a startup become before investors stop describing its losses as growing pains?
Flipkart, founded by Sachin Bansal and Binny Bansal in 2007, makes that question difficult to avoid. Nearly two decades later, the business that helped establish India’s appetite for online shopping reported FY26 operating revenue of ₹1,45,880 crore—and a net loss of ₹8,468 crore.
Its scale is extraordinary. So is the patience its business has required.
As Flipkart prepares for a potential listing, its accounts deserve scrutiny beyond the familiar celebration of rising revenue and narrowing losses. They offer a test of the profitability narrative surrounding Indian startups: what, precisely, should years of investment eventually produce?
Zeroing In on ECI
09 Oct 2026 - Vol 05 | Issue 41
Constitutional legitimacy versus political opportunism
AMAZON TOOK YEARS. HOW MANY?
Amazon is the inevitable comparison whenever an ecommerce company’s losses come up.
The comparison needs dates.
Founded in 1994, Amazon recorded its first profitable quarter in the final three months of 2001. Its first profitable full year followed in 2003, with approximately $35 million in net income—roughly nine years after founding. It had listed in 1997, several years before that milestone.
The initial annual profit was thin. Amazon’s annual report also acknowledged that favourable currency effects helped it cross into positive territory. Its history demonstrates both the value of patient capital and the importance of examining what sits behind a profit figure.
It does not supply a universal timetable. India’s purchasing power, retail structure and delivery economics differ from America’s. Flipkart’s consolidated group also includes businesses beyond its original marketplace.
But “Amazon lost money too” becomes an incomplete argument when the comparison omits how long it took—and what happened next. Patience needs evidence of progress.
FLIPKART IS MAKING PROGRESS
Flipkart’s results contain that evidence.
Operating revenue grew 18.2% in FY26. EBITDA losses narrowed 21.5% to ₹5,891 crore, according to the supplied financial breakdown. Net losses declined by a much smaller 2.1%, or ₹178 crore.
The company’s explanation matters. It says adjusted operating business losses narrowed by approximately ₹1,600 crore, while higher finance costs, deferred-tax-asset derecognition and exceptional items moderated the improvement in net losses. Its adjusted operating margin improved from negative 7.7% to negative 5.4%.
Those adjustments differ from the EBITDA calculation in the reported financial breakdown. They should be labelled separately.
The underlying message is nevertheless clear: operating economics improved more substantially than the bottom-line movement suggests.
That strengthens the question shareholders should ask. How much further must those economics improve before the consolidated business can sustain a net profit?
DOES EVERY NEW BUSINESS RESTART THE CLOCK?
A large platform rarely reaches a point where investment simply stops.
Customers expect faster deliveries. Competitors enter new categories. Technology and fulfilment networks require spending. Flipkart Minutes adds another competitive front against established quick-commerce businesses.
The investment case can be sound. An incumbent that refuses to expand risks losing customers to a newer proposition.
The difficulty is separating investment that creates future returns from spending required merely to maintain competitive position.
Investors need to understand whether established businesses generate enough earnings and cash to fund the next expansion; which newer operations require support; and what milestones justify that support.
Otherwise, profitability remains permanently attached to the next stage of growth.
Flipkart’s consolidated accounts now bring 25 subsidiaries under the Indian reporting entity following its redomiciliation. That broader view is valuable, but it also makes comparisons with older standalone marketplace results misleading. The right question concerns the economics of the group shareholders would own.
OTHER MARKETS OFFER OTHER ANSWERS
Latin America’s MercadoLibre supplies a useful second comparison.
Its business combines commerce, logistics and financial services across markets with their own infrastructure and economic challenges. In 2025, it generated approximately $28.9 billion in net revenues and financial income and almost $2 billion in net income.
The financial-services component makes a direct comparison with Flipkart inappropriate. The broader lesson is that an emerging-market platform can keep expanding its ecosystem while reporting substantial consolidated earnings.
Amazon’s history illustrates the time required to establish profitability. MercadoLibre illustrates the possibility of combining investment with current profits.
Neither proves what Flipkart should earn today. Both raise the standard of evidence needed to explain why its earnings remain negative.
SIZE IS AN ACHIEVEMENT. RETURNS ARE ANOTHER.
Flipkart helped build consumer trust in ecommerce, supported sellers and created delivery infrastructure. Its influence extends through founders, employees and investors across India’s startup economy.
Those achievements explain its importance. Financial returns require their own assessment.
FY26 advertising revenue reached ₹9,597 crore, while logistics, warehousing and shipping contributed ₹23,059 crore. These offer additional ways to earn from the group’s audience and infrastructure. Revenue figures alone, however, do not establish how profitable either activity is.
Similarly, ₹1.46 lakh crore in operating revenue includes traded-goods sales. It cannot be compared casually with a marketplace that recognises commissions rather than the full value of merchandise.
The debate needs consistent measures: net earnings, operating performance, cash generation and returns on invested capital.
A quarterly profit at one subsidiary, an adjusted group milestone and durable consolidated profitability answer different questions.
WHAT SHOULD PUBLIC INVESTORS BUY?
A loss-making company can justify a listing. Amazon itself did.
The obligation is to explain why capital committed today should produce attractive future returns—and make that explanation measurable.
For Flipkart, that means visibility into mature-business economics, the cost of expansion and the route from improving margins to sustainable earnings.
It also means resisting an easy extrapolation. Flipkart’s experience does not establish that every Indian startup must endure similarly long losses. Business models have different capital requirements and opportunities.
Its significance is as a demanding case study. One of India’s defining startups has achieved enormous scale, attracted a powerful global owner and improved its operating performance. A substantial annual loss remains.
India’s profitability debate should start there.
Nineteen years after founding, Flipkart has proved it can build a market. The next task is demonstrating what that market can consistently earn.