Why Can’t Pricier iPhones Protect Apple’s Profit Machine?
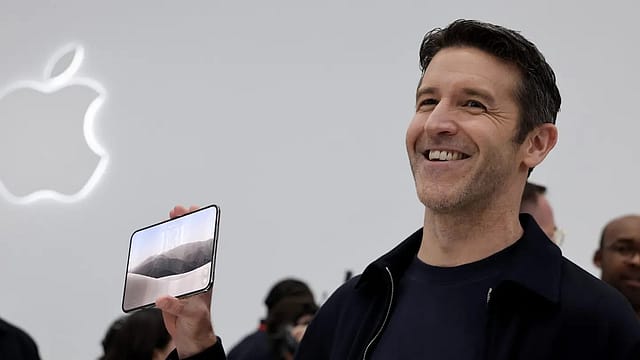
Apple, the company behind the iPhone and Mac, reported record September-quarter revenue on November 2 in the US. Sales rose 12% to $114.5 billion, while net profit increased nearly 12% to $30.7 billion.
Yet investors were unsettled by what came next. Apple forecast a lower gross profit margin for the December quarter, citing rising memory-chip costs and expenses associated with Siri AI. Shares fell as much as 4% during the earnings call before recovering some ground, according to Reuters.
It was John Ternus’s first earnings report as chief executive after taking over in September. His challenge is to sustain growth while the cost of delivering Apple’s products and services climbs.
If sales and profit rose, what worried investors?
The outlook for the next quarter.
Apple expects its gross margin to fall to 45–46%, from September’s 47.9%. It also expects slower growth in Services, the business that includes subscriptions, cloud storage and App Store-related income.
The Era of Forever Wars
30 Oct 2026 - Vol 05 | Issue 44
Coping with an explosive Middle East
Investors buy shares partly for the earnings they expect a company to produce in future. A strong quarter can therefore be followed by a falling share price if the forecast raises doubts about future returns.
The warning concerns how efficiently Apple can turn sales into profit. It does not mean the company has reported a loss.
What does a falling margin actually mean?
It means less money left from each dollar of revenue after paying the direct costs of supplying products and services.
At a 47.9% gross margin, Apple retains $47.90 from every $100 of sales before expenses such as research, marketing and tax. At the midpoint of its December forecast, 45.5%, that would become $45.50.
A company can still increase its total profit if sales rise enough. But it has to generate more revenue to compensate for keeping a smaller share of each sale.
Why aren’t higher prices enough?
Because Apple’s costs are rising too.
Ternus said price increases across several products, including iPhones in September, had partly offset higher memory costs. Cheaper inventory purchased earlier also helped, but that protection is expected to diminish.
Think of a shop selling stock it bought before a supplier raised prices. Its existing inventory gives it breathing room. Replacing that stock at the new price changes the calculation.
Apple faces a similar decision: absorb more costs, find savings elsewhere or ask customers to pay more. Raising prices can protect margins, but risks persuading some buyers to postpone replacing a device.
How is the AI boom reaching the iPhone’s component bill?
Through competition for memory and manufacturing capacity.
Memory chips help devices hold and process information. AI data centres need enormous amounts of memory and storage to run their systems.
Micron, a major memory producer, says AI-driven demand is expanding faster than the industry can increase supply. Its annual filing also explains that high-bandwidth memory, used in advanced computing, requires more manufacturing resources per unit of capacity than conventional memory.
These are different products, but they draw on parts of the same manufacturing industry. Expanding one category can affect how much capacity is available for others.
That connects the rush to build AI infrastructure with pressure on consumer-electronics costs. Apple’s brand strength cannot manufacture additional industry capacity overnight.
Does Apple’s own AI create another bill?
Yes. Apple identified costs associated with expanding Siri AI as another factor affecting its margin outlook.
Chief financial officer Kevan Parekh said the cloud costs of running those services would appear in Services costs. Ternus also described plans for users to purchase expanded access to some server-based AI features.
That creates a business test: will customers use the new capabilities enough to justify the expense, and will enough of them pay for additional access?
Why does Services growth matter so much?
Because Services contributes disproportionately to Apple’s gross profit.
Our calculations from Apple’s financial statements show that Services generated roughly 28% of September-quarter revenue but about 44% of gross profit. Its gross margin was approximately 76%, compared with 37% for products. These figures are before company-wide operating expenses.
That makes subscriptions and other service income especially valuable when hardware costs rise.
Services revenue still grew approximately 10% to $31.6 billion. But Apple forecasts growth of 8–9% in the December quarter.
A slowdown in such a profitable business makes the pressure on hardware harder to offset.
Did a temporary benefit make the results look stronger?
Yes. Tariff refunds added approximately one percentage point to September’s gross margin and five cents to earnings per share.
Removing that margin benefit produces roughly 46.9%. Comparing this with December’s forecast gives a clearer view than treating the entire reported decline as a fresh deterioration.
The refunds helped the quarter. They cannot be assumed to provide a recurring improvement in the underlying business.
How does India fit into Apple’s growth story?
India provided an encouraging result. Apple reported its highest-ever quarterly revenue in the country, alongside records in Mac and Services. It also recorded a September-quarter high for iPhone upgraders in India.
These are signs of demand extending across its business. Apple’s published financial tables, however, do not give India a separate revenue figure. They therefore cannot establish how much India could offset pressure elsewhere.
For Indian buyers, the results also do not announce another price increase. Global cost pressures are a reason to watch pricing, availability and upgrade offers.
What happens next?
The December quarter will test whether Apple can sustain demand while managing its higher costs. Apple expects revenue growth of 7–10%, alongside a gross margin of 45–46%. Those are forecasts; the quarter’s actual results are still to come.
The evidence to watch is whether margins land within that range, Services growth stabilises and customers keep upgrading as prices rise. Apple must also show whether its AI features generate enough additional income or product demand to justify their running costs.
The next results will show how much of today’s warning becomes tomorrow’s financial performance.