Too Early for Revenue? What Deep-Tech Startups Must Prove Instead
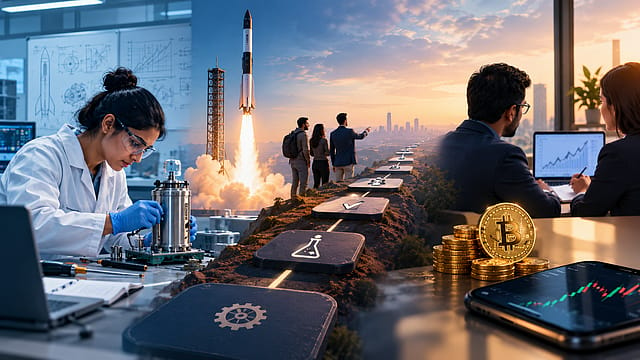
A startup developing a reusable rocket can spend heavily while its most important achievement produces no ticket, invoice or delivery to a paying customer.
An engine might restart successfully. A recovery system might survive testing. Each result can bring the business closer to being possible, even while revenue remains unchanged.
That creates a reasonable problem for investors: the income statement may tell them how quickly money is leaving, while revealing little about whether the technology is becoming more valuable.
It also creates room for an unreasonable excuse. A founder can keep pointing to the future without explaining what the latest expenditure has established.
Look Who's Talking Regime Change
23 Oct 2026 - Vol 05 | Issue 43
The useful question is what a company should prove while sales are still a poor measure of progress.
WHAT CASADO IS ARGUING
In an October 28 essay, Martin Casado, a general partner at Andreessen Horowitz, wrote: “Tech waves nearly always precede figuring out the business models.”
His subject is venture investing broadly, including early infrastructure companies. Applying the argument to deep tech is an analytical extension, rather than a claim that the essay offers a specific rulebook for rockets or biotechnology.
Casado distinguishes investment approaches centred on financial performance, technology’s capacity to create markets, exceptional founders and speculative pricing. His concern is that investors can mix incompatible justifications without a consistent philosophy.
He also recognises that financial analysis becomes more relevant as businesses mature. His argument does not establish that commercial evidence can be postponed indefinitely.
The practical challenge follows from that distinction. If revenue is premature, investors need other observable evidence, with standards matched to the risk they are funding.
INDIA HAS A CONCRETE EXAMPLE
On September 25, India’s Technology Development Board announced an agreement to provide ₹200 crore of financial support to Agnikul Cosmos under the Research Development and Innovation Fund.
The support is through optionally convertible debentures. The stated project is the development of a reusable Agnibaan launch vehicle, progressing from Technology Readiness Level 4 and above towards Level 8.
Those details matter more than treating the amount as another funding headline.
Technology-readiness levels describe stages of technical maturity. The agreement identifies an intended progression in capability. It does not say that the proposed fully reusable system already operates commercially.
Nor is the support customer revenue or an unconditional grant.
This provides an Indian example of capital being committed against a development objective. The announcement does not, by itself, reveal the full disbursement conditions, independent verification arrangements or commercial returns.
Those are precisely the details an assessment should seek.
A DEMONSTRATION NEEDS A NEXT TEST
Before revenue becomes meaningful, the first question is whether the underlying result can be reproduced.
Consider a hypothetical startup developing a new battery. A laboratory cell with impressive performance is useful evidence. Repeated results across independently tested cells would establish more. Consistent production at a larger scale would address another uncertainty.
The same principle applies to industrial AI. A successful demonstration on selected data leaves unanswered whether the system performs on unfamiliar inputs under customer conditions.
Investors should be able to identify what improved, against which benchmark, under whose supervision and with what failure rate.
A presentation that announces a breakthrough without specifying the conditions makes future progress difficult to assess.
The next round should ideally finance an experiment capable of changing the investment decision. If every possible result is interpreted as encouragement, the milestone has little disciplinary value.
CUSTOMER PROOF CAN ARRIVE BEFORE SALES
An early customer can contribute evidence without placing a large order.
Useful signals include providing equipment or data for testing, allocating engineering staff, agreeing acceptance criteria and identifying the person who controls the eventual budget.
These commitments have costs for the customer. They can reveal seriousness beyond a supportive meeting.
A letter of intent still needs reading. Does it specify what must work, at what price and by when? Can either side withdraw without consequence? Is the eventual purchase dependent on regulatory approval or another company’s spending decision?
A paid pilot adds evidence, but its purpose matters. A small experiment funded from an innovation budget may have no agreed route into ordinary procurement.
The investor’s task is to establish how a successful experiment becomes a product the organisation can buy.
NASA SHOWS HOW PATIENCE CAN HAVE CONDITIONS
There is a useful historical example in NASA’s Commercial Orbital Transportation Services programme.
NASA’s inspector general described agreements linking payments to completed milestones, including design reviews, testing and demonstration flights. SpaceX and Orbital Sciences participated in that development effort.
The arrangement did not eliminate technical uncertainty. It made progress observable before a mature commercial service existed.
It also allowed a stopping decision. NASA terminated its agreement with Rocketplane Kistler in 2007 after the company failed to achieve financial and technical milestones. By then, NASA had spent $32.1 million.
This is a public development programme, with objectives and resources different from a venture fund’s. Its relevance is the structure: agree what the next payment is intended to establish, verify the result and retain the ability to stop.
A long development horizon can still contain decisions with deadlines.
THE ENGINEERING MUST EVENTUALLY MEET THE COST
Technical success can leave a company commercially stranded.
A device may work while costing more to manufacture than customers will pay. A robot may perform a task while needing too much supervision. A process may produce the desired material with unacceptable rejection rates.
Early investors cannot require final unit economics before the process exists. They can require a transparent account of current costs and the assumptions behind projected improvements.
Which cost falls with volume? Which depends on a scientific advance still to come? What happens if a supplier’s price remains unchanged?
That separates demonstrated improvement from a spreadsheet assumption.
It also prevents revenue from becoming misleading when it eventually arrives. A bespoke engineering contract can generate sales without establishing that the product can be sold repeatedly at an attractive margin.
THE INVESTOR NEEDS A MILESTONE TOO
India’s Accel Atoms explicitly welcomes pre-product and pre-revenue founders. Its published selection criteria include the team, a clear customer need and the market opportunity.
That demonstrates that backing a company before sales is already an identifiable investment practice. It does not establish that every such company merits funding or that accepting the initial application guarantees follow-on capital.
The investor also needs to explain whether the fund can support the next stage.
A technically successful company can still face a financing gap if the next test requires more capital than existing backers can provide. Founders should understand the fund’s capacity, decision process and expectations as the business develops.
Otherwise, the company may meet the milestone and discover that its financing plan depended on a different investor arriving.
WHAT SHOULD THE NEXT CHEQUE BUY?
A useful review would identify the largest unresolved risk, the test intended to reduce it, the money and time required, and the consequences of success or failure.
Those answers will change as the company advances. Technical evidence should increasingly connect with production, customer acceptance and a plausible way to earn money.
Revenue will eventually become central. Before then, investors can ask whether each expenditure is making the next commercial decision better informed.
The strongest case for patient capital is a sequence of results that earns the patience.