Maruti’s SUV Sales Are Booming. Where Is the Profit?
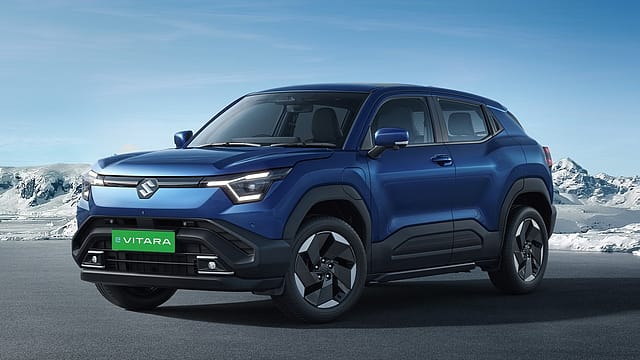
Maruti Suzuki sold almost 1.46 lakh more vehicles in the September quarter than it did a year earlier. Its utility-vehicle business expanded by more than half. Net sales crossed ₹50,000 crore. Yet operating profit fell by ₹578 crore.
For India’s biggest carmaker, the uncomfortable number sits beneath the record volumes. Divide operating profit by vehicles sold, and Maruti generated roughly ₹40,245 per vehicle in Q2FY27, against ₹61,393 a year earlier. That is a decline of 34.4%, calculated from its investor presentation.
This measures company-wide operating profit against total vehicle sales, including domestic sales and exports. It cannot tell us what Maruti makes on a particular SUV or hatchback. It does capture how much less operating profit the company generated relative to the number of vehicles it sold.
The question is how much protection its growing utility-vehicle business can provide when manufacturing costs rise this quickly.
Look Who's Talking Regime Change
23 Oct 2026 - Vol 05 | Issue 43
More utility vehicles, little movement in sales per vehicle
Maruti’s utility-vehicle volumes rose 52.3% to 2,36,807 in Q2FY27. The category accounted for 40.2% of its domestic sales, whose total also includes sales to other manufacturers. Its combined mini, compact and midsize passenger-car basket grew 31.9%.
Utility vehicles were becoming a larger part of the business. Yet dividing company-wide net sales by total vehicles sold produces an almost unchanged figure: approximately ₹7.27 lakh, compared with ₹7.29 lakh a year earlier.
This aggregate ratio includes the effects of exports, model and variant mix, and other components of net sales. It should not be read as an average showroom price. Maruti’s exports fell 2.1% during the quarter, changing the composition of overall sales.
The figures, therefore, cannot establish that its SUVs became less profitable. What they show is that a substantially larger utility-vehicle business did not translate into higher aggregate net sales per vehicle or protect company-wide operating earnings.
Maruti lists improved realisation among the factors supporting profitability. The presentation does not provide a detailed bridge separating the effects of pricing, domestic model mix and exports. That leaves an important question unanswered: how much additional revenue is its changing portfolio generating, and how much of that gain is being consumed by costs?
The bill consuming the gains
Material costs absorbed 79.9% of Maruti’s net sales, up from 75.7% a year earlier. For every ₹100 of net sales, approximately ₹20.10 remained after material costs, compared with ₹24.30 previously. Employee costs, other expenses and depreciation still had to be covered, while other operating income also contributed to earnings.
The company reduced employee costs and other expenses as a proportion of net sales. Those savings could not offset the increase in the material-cost ratio.
Operating EBITDA margin fell from 12.7% to 9.4%. After depreciation, operating EBIT margin fell from 8.4% to 5.5%.
Maruti attributes the pressure to adverse commodity prices linked to the West Asia conflict and unfavourable foreign-exchange movements. Lower non-operating income, caused by mark-to-market losses on invested surplus, further depressed net profit.
Investment losses explain part of the bottom-line decline. The fall in operating profit shows that the pressure also reached the underlying business.
What the rivals can tell us so far
A complete September-quarter comparison with Maruti’s passenger-vehicle rivals will have to wait. Mahindra & Mahindra’s Q2FY27 results are scheduled for November 5, while Tata Motors Passenger Vehicles is scheduled to consider its results on November 13. Tata’s commercial-vehicle results, released on October 23, cover trucks and buses and cannot serve as a direct comparison for this story.
The preceding quarter offers context, although it cannot establish how those businesses performed through the same July–September conditions.
In Q1FY27, Mahindra’s SUV volumes increased 15%, while standalone automotive profit before interest and tax was broadly unchanged at ₹2,212 crore. Its automotive PBIT margin, excluding electric-SUV contract manufacturing, fell 170 basis points to 8.3%. Mahindra’s automotive business also includes commercial vehicles.
Hyundai Motor India’s Q1FY27 consolidated EBITDA margin fell to 9.3%, from 13.3% a year earlier. Temporary production disruptions and export pressure linked to the West Asia conflict affected its performance.
Tata’s domestic passenger-vehicle business recorded a different trajectory. Q1FY27 revenue increased 64.8% to ₹17,930 crore, and EBITDA margin improved 30 basis points to 4.3%. EBIT margin also improved, although it remained negative at minus 0.5%. Tata said elevated commodity costs and foreign-exchange movements moderated the improvement.
These earlier disclosures show the different pressures and starting points across manufacturers. They do not support a verdict on which company has handled the September quarter best. Maruti’s latest results must first be judged against its own performance.
A sequential recovery worth watching
There is encouraging evidence in Maruti’s latest quarter. Compared with Q1FY27, operating profit increased 10.8%, while operating EBITDA margin recovered from 8.6% to 9.4%. Its material-cost ratio improved from 80.5% to 79.9%.
The year-on-year squeeze, therefore, comes alongside a sequential recovery.
The presentation lists improved realisation, cost reductions and a favourable fixed-cost effect from inventory accretion among the factors supporting that recovery. When inventory builds, some production costs can remain in stock on the balance sheet until the vehicles are sold. The presentation does not quantify the contribution of that effect.
That makes the durability of the improvement worth watching. Pricing and cost reductions will need to sustain margins as production, inventory and sales change.
Across the first half of FY27, the gap between growth and profitability remained substantial. Vehicle sales increased 27.9% and net sales rose 31%, while operating profit declined 15.7%.
Maruti has demonstrated that it can sell significantly more vehicles and expand its utility-vehicle business. The next results will need to show whether it can retain more of the revenue those vehicles bring in.