Mark Zuckerberg’s Meta Deal Explained: How to Sell Shares & Still Stay Boss
A share of a company usually comes with two things: a financial stake and a say in how it is run.
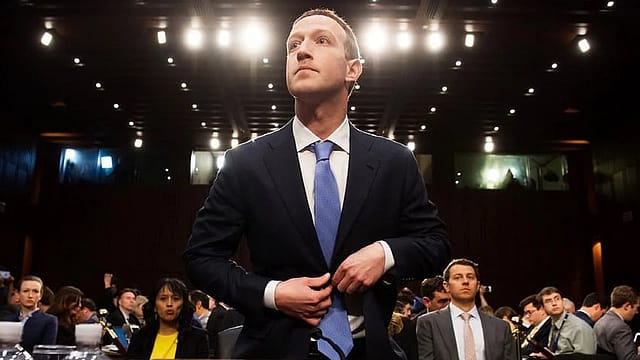
Mark Zuckerberg’s latest deal with Meta separates the two. He gets room to sell some of his investment while keeping his grip on the company. Meta gets a new kind of share it can use to fund its ambitions. And the board gets a commitment that its founder will stay close to headquarters.
Getting there was apparently quite a dinner conversation.
According to The Washington Post’s account of Meta’s disclosures, negotiations became so strained that directors overseeing the talks discussed resigning. Zuckerberg later told a wider group of directors that he planned to put his Palo Alto home up for sale. The possibility of his departure from California added urgency to the negotiations.
Losing Memory
16 Oct 2026 - Vol 05 | Issue 42
The making of a medical and social emergency
So, what exactly have they agreed—and how can someone sell part of a company without selling part of their power?
FIRST, HOW DOES ZUCKERBERG CONTROL META?
Because all Meta shares do not carry the same voting rights.
Its Class A shares carry one vote each. Class B shares carry ten. Zuckerberg’s supervoting stock gives him roughly 60% of the votes despite owning only about 13% of the company.
Think of a housing society where most owners get one vote per flat, but one owner gets ten. Counting flats alone will tell you very little about who wins the election. That is why “majority shareholder” can be misleading here. Zuckerberg’s decisive advantage is his majority of voting power.
WHAT PROBLEM DOES SELLING SHARES CREATE FOR HIM?
Selling supervoting shares can weaken that advantage.
Zuckerberg wants access to the wealth tied up in Meta while preserving his ability to steer it. Meta, meanwhile, wants flexibility to bring in investors and use stock for employees and acquisitions.
The solution is a third category: Class C shares, which carry an economic interest but no ordinary voting rights. Meta announced the new class alongside its October 21 results. Someone buying those shares can benefit financially if the business prospers. They do not receive the usual voting say over its direction.
WHY DOES META NEED THIS NOW?
Artificial intelligence is making the company’s ambitions extraordinarily expensive.
Meta reported $34.91 billion in capital expenditure, including finance-lease principal payments, in the September quarter. Its operating activities generated $32.79 billion in cash. After that investment spending, free cash flow was negative $2.12 billion.
Put simply, the business brought in an enormous amount of cash, then spent even more on long-term assets.
Non-voting stock gives Meta another funding tool. It can sell an economic stake to investors without handing them additional votes over Zuckerberg’s plans. That does not make the investment cheaper. It makes raising money less disruptive to his control.
DOES EVERY SHAREHOLDER GET THESE NEW SHARES?
Yes. This is not an allocation reserved for Zuckerberg.
Meta’s filing says each existing Class A and Class B share will receive one Class C share. The revised charter is expected to take effect on January 19, 2027, with distribution following its effectiveness.
But receiving twice as many shares does not automatically double anyone’s wealth.
Imagine cutting a pizza into sixteen slices instead of eight. There are more slices. There is still one pizza. Likewise, distributing the new shares does not itself bring fresh money into Meta. Raising money would require a subsequent transaction, such as selling shares to investors.
THEN WHAT DID THE BOARD MAKE ZUCKERBERG GIVE UP?
Immediate freedom to sell most of his new Class C holding without consequences for his voting position.
Under the agreement, 20% of his initial allocation is freely saleable. The remaining 80% is subject to restrictions linking sales to corresponding transactions involving voting shares, with specified exceptions and credits.
The restriction gradually loosens. Each qualifying quarter releases an amount equal to 2.5% of his original Class C allocation, provided he serves full-time on the executive team or as executive chair throughout that quarter. Releasing the entire restricted portion therefore requires 32 qualifying quarters: eight years.
The bargain is straightforward: stay involved, and progressively gain more freedom to sell.
WHERE DOES CALIFORNIA’S WEALTH TAX COME IN?
A billionaire can be enormously wealthy without having billions sitting in a bank account. Much of that wealth may be company stock.
Reuters reported that California’s proposed one-time 5% billionaire wealth tax raised the prospect of a substantial bill for Zuckerberg. Selling voting shares to meet it could weaken his control. Selling non-voting shares offers another route.
The arrangement does not cancel a tax bill. It provides a way to raise cash while retaining votes.
Separately, Zuckerberg committed to remain resident in California—or another jurisdiction where Meta maintains its headquarters—for eight years while the leadership condition is met, subject to material unforeseen circumstances.
IS THIS A HUGE NEW PAY PACKAGE?
The final agreement leaves his existing compensation arrangement unchanged, according to Meta’s preliminary information statement. It instead combines share-sale restrictions, their gradual release, the residency commitment and provisions for potential future Class C dividends.
Calling it simply a pay rise misses the mechanism. Its value to Zuckerberg lies in greater flexibility over his wealth while protecting his authority.
DID ORDINARY SHAREHOLDERS GET TO DECIDE?
There was shareholder approval, but through written consent rather than a fresh vote at a shareholder meeting. Meta’s filing says the necessary shareholders approved the change on October 20.
Zuckerberg’s voting majority is crucial to understanding that distinction. Other investors can own a substantial economic stake collectively and still lack the votes to defeat him.
SO, IS THIS A GOOD DEAL FOR INVESTORS?
That depends on what they want from Zuckerberg.
Investors who trust his judgement may welcome a structure that lets Meta raise capital while maintaining consistent leadership. Investors worried about expensive mistakes may see a stronger barrier between supplying money and influencing how it is spent.
There is also a distinction worth keeping clear: non-voting shares can preserve voting control while still diluting existing investors’ economic ownership when additional shares are issued to outsiders.
Meta gains financing flexibility. Zuckerberg gains selling flexibility. The board secures conditions intended to keep him involved. Other shareholders are being asked to keep backing his judgement—even as the company creates more shares whose owners cannot vote on it.