Small Reactors, Big Power: What’s Behind the US-Japan-South Korea Nuclear Push?
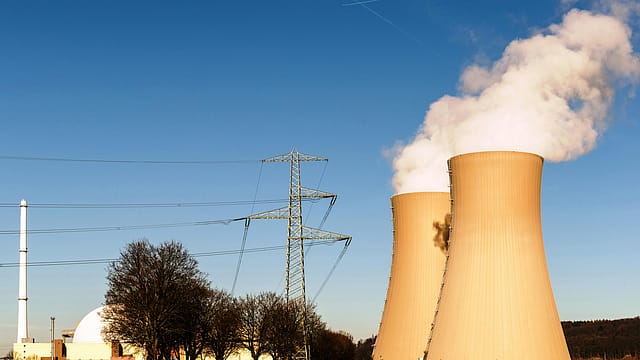
Can nuclear power become cheaper by learning to repeat itself?
That question sits beneath a new American, Japanese and South Korean push to take small modular reactors, or SMRs, to other countries. Its answer could influence how Europe powers its industries, how emerging economies expand their electricity systems and how India turns its own small-reactor ambitions into working plants.
The proposition is compelling: settle on a design, manufacture standardised components, build a succession of reactors and make each project benefit from the last.
The difficulty is getting that succession started. Customers want evidence that reactors can be delivered affordably. Manufacturers need orders to establish the production system that is supposed to make them affordable.
Rise of the Pivotal Power
18 Sep 2026 - Vol 05 | Issue 38
The BRICS declaration is a strategic victory for Modi
The latest alliance is an attempt to help bridge that gap. It also raises a question that an investment headline cannot answer: who will commit to buying the electricity?
What Has Actually Been Announced?
On September 23, the US, Japan and South Korea announced an implementation plan supporting their July 7 memorandum on deploying SMRs in other countries.
Alongside it came an industry cooperation framework involving GE Vernova, Hitachi, Samsung C&T and Poland’s SGE to advance the BWRX-300 reactor across Europe. The US State Department said the consortium aimed to encourage more than $150 billion in reactor investments in the coming years.
These are related developments with different functions: government cooperation on overseas deployment, and a commercial framework centred on a particular reactor.
The distinction matters. The announcement does not establish that $150 billion has been raised, that reactors worth that amount have been ordered, or that the necessary sites have secured construction licences. It describes an ambition and a framework for pursuing it.
How Small Is “Small”?
The International Atomic Energy Agency describes SMRs as reactors with electrical capacity of up to 300 megawatts per unit. “Modular” refers to systems and components that can be assembled in factories and transported for installation.
They generate energy through nuclear fission. The innovation lies partly in how plants are designed, manufactured and deployed. A smaller unit can suit a grid or customer unable to accommodate a much larger reactor; additional units can follow as demand grows.
Consider a factory buying machinery in stages instead of committing to its entire eventual production capacity immediately. That is the appeal of incremental deployment. But the analogy has limits. A reactor still needs a licensed site, trained operators and supporting infrastructure. Modular construction does not turn a nuclear power station into an appliance.
Why This Reactor?
The European initiative centres on the BWRX-300, a 300-megawatt water-cooled reactor developed by GE Vernova Hitachi.
Its design uses natural circulation to move cooling water through the core. The developer also emphasises its use of commercially available fuel, reducing the need to develop a new fuel product alongside a new plant.
That is a significant commercial choice. A project depending on several technologies becoming available simultaneously has more opportunities for delay.
The company describes passive safety systems that use natural processes to remove heat during specified emergencies. Such features are part of the design’s safety case; regulators must assess whether the complete plant meets their requirements.
SMR is, therefore, a category, rather than a single technological promise. Evidence about one design cannot automatically establish the cost or performance of another.
The Fleet Is the Business Model
The most consequential word in the announcement may be “fleet”.
A single smaller reactor produces less electricity than a large one. Its costs cannot be assumed to shrink in the same proportion. Developers are betting that repeat production, simpler designs and experience gained across successive projects can improve that calculation.
The European Commission identifies serial manufacturing and factory assembly as potential sources of savings. It also sees applications in industrial heat, district heating and replacing fossil-fuelled generation.
The alliance’s commercial logic follows: combine the capabilities of several countries and assemble enough projects to support repeated construction.
Yet standardisation can weaken if every customer requires substantial redesign. A useful test will be how much of each successive plant genuinely repeats the previous one.
Why Governments Care Who Builds Them
Electricity demand is growing as economies electrify and data centres expand. Nuclear power offers low-emissions generation available around the clock, complementing variable renewable sources.
There is also a supply-chain concern. In its January 2025 nuclear report, the International Energy Agency found that 48 of the 52 reactors whose construction had begun worldwide since 2017 used Chinese or Russian designs. That is a dated snapshot of reactor construction across sizes, rather than a count of SMR projects.
It nevertheless helps explain the strategic appeal of another export offering.
A reasonable reading of the trilateral push is that the participants want influence over the next generation of nuclear supply chains as well as reactor sales. The State Department explicitly connects the initiative with shared security interests.
For buyers, the practical question extends beyond the plant: how dependable will the relationships supporting it be over decades?
Canada Is the Test to Watch
The BWRX-300 has a concrete reference project at Darlington in Ontario.
Ontario Power Generation’s published plan envisages four units producing a combined 1,200 megawatts, subject to approvals for the additional reactors. The first received a construction licence in April 2025; OPG targets connection to the grid by the end of 2030.
The budget is C$20.9 billion for all four. The first reactor accounts for C$6.1 billion, with another C$1.6 billion for systems and services shared across the planned fleet. OPG expects costs to decline on subsequent units as experience accumulates.
Those distinctions matter. Assigning every shared cost to the first reactor would distort comparisons; assuming later savings have already been achieved would be equally misleading.
Darlington will help answer whether a design can move from drawings to construction, commissioning and repeat delivery on the terms its supporters expect.
A successful first unit would be significant. The cost and speed of the next ones will test the fleet argument.
The Customer Can Still Walk Away
The American experience offers a warning.
In November 2023, NuScale Power and Utah Associated Municipal Power Systems terminated their Carbon Free Power Project. Their joint announcement said sufficient subscription to proceed with deployment appeared unlikely.
That was a different reactor design and project. It does not predict the BWRX-300’s outcome. It does demonstrate that technological progress alone cannot secure a customer base.
SMR economics must pass two tests: can a project be financed, and can its electricity attract buyers at the required price?
The IEA identifies predictable revenues and arrangements such as long-term electricity purchase agreements as important to nuclear financing. Smaller projects could broaden investor participation, but that potential depends on proving early plants.
For an industrial customer, “small” is unlikely to be the decisive selling point. Affordable, dependable and delivered when needed will matter more.
What About Waste, Safety and the Climate Clock?
A smaller reactor remains a nuclear facility. The deployment case must include regulation, security, waste management and eventual decommissioning. Design improvements do not remove those responsibilities.
There is also an argument about timing.
In a 2024 assessment, the Institute for Energy Economics and Financial Analysis argued that SMR costs and delays made them a poor near-term decarbonisation bet. It warned that spending on uncertain reactor projects could divert resources from renewable generation and storage available sooner.
That criticism deserves to be tested against actual projects, alongside developers’ claims.
The useful comparison is between complete options for supplying dependable, low-emissions power on a particular grid. Construction time, transmission, storage, backup and financing all belong in the assessment.
An SMR expected in the next decade cannot solve a power shortage this year.
India’s Stake Goes Beyond Buying Reactors
India has committed ₹20,000 crore under its Nuclear Energy Mission to SMR development and deployment, with a target of at least five indigenous SMRs operating by 2033.
An August 5, 2026 parliamentary reply identified BARC’s BSMR-200 and SMR-55 power-reactor programmes, alongside a high-temperature reactor intended to supply heat for hydrogen production. It said Tarapur had been approved by the Atomic Energy Commission as the site for the two power-reactor designs.
The reply also placed the establishment period at 60–72 months after administrative and financial sanction. That qualification matters when assessing the 2033 target.
For India, the overseas alliance creates both a benchmark and a strategic choice. Domestic programmes will need to demonstrate their own costs and delivery schedules while deciding where international cooperation helps.
The editorial question is larger than whether India should import a particular machine: how much value can Indian engineering, manufacturing and operating capability capture as this market develops?
The Proof Will Be in the Second Reactor
The alliance’s progress should be judged through milestones: committed customers, financing, licences, construction, electricity delivered and lower costs on repeat units.
Each milestone resolves a different uncertainty. A memorandum cannot substitute for them.
Small reactors offer a plausible route to a more repeatable nuclear industry. The first working plant can establish that a design performs. The next plants must show that repetition improves the economics. That is where the promise of “small” will meet the electricity bill.
With inputs from ANI & agencies