Headwinds Or Tailwinds: Which Way Is The Indian Economy Headed?
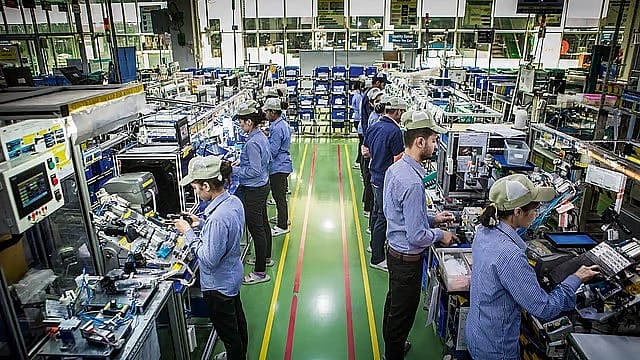
Is the Indian economy booming or struggling? I get a mixed picture. On the one hand, I see people queuing outside Apple stores to buy expensive iPhones. On the other, the Sensex, widely regarded as a barometer of the economy, has delivered a negative return of over 11% in the last 12 months.
Global agencies are optimistic about India and expect our GDP to grow by around 7%. But strangely, this optimism has had little bearing on the rupee, which has weakened to around Rs 95 against the dollar. Automobile sales are accelerating, but food inflation is eating into household budgets. India is the fastest-growing major economy in the world. But do millions of Indians feel they are moving forward? Not really, going by the per capita income yardstick, which stands at around $2,800.
Zeroing In on ECI
09 Oct 2026 - Vol 05 | Issue 41
Constitutional legitimacy versus political opportunism
Our country may be experiencing an economic boom at the macro level, but is the average Indian experiencing that boom at the micro level?
Has the standard of living of Indian families improved? Yes and no.
One class is buying high-end cars and luxury apartments, jet-setting across the world and hosting big fat weddings. Meanwhile, a large section of the burgeoning middle class continues to worry about the next EMI, school fees, medical bills and job security.
We constantly hear the Modi government talk about India becoming the world's third-largest economy, a $5-trillion economy and, eventually, achieving the vision of Viksit Bharat by 2047.
Going by the news and events unfolding around us, one is tempted to ask: Which is stronger — the headwinds or the tailwinds? Let's examine.
Among the most pressing concerns is the below-average monsoon, along with El Niño-related risks. This threatens the agricultural sector, rural incomes and food prices. Adding to these woes are rising oil prices, thanks to the West Asia crisis, with India's average crude oil purchase cost reportedly touching $110 per barrel. This, in turn, raises our import bill and stokes inflation. In FY26, India's oil import bill stood at $135 billion.
This is worrying the government of the day. So much so that, to prevent the balance of payments from going haywire, Prime Minister Narendra Modi has reportedly been urging Indians to postpone non-essential gold purchases for a year. For the record, India imported gold worth $72 billion in FY26.
Now, what about the tailwinds? What is going right for India?
Just look at the numbers. GDP growth in Q1 FY27 stood at 7.8%, while retail inflation climbed to 5.54% in September 2026. The RBI's October monetary policy projected real GDP growth of 7.1% for FY2026–27.
The good news is that tax collections have also been buoyant. GST collections in September 2026 recorded a 14.7% year-on-year jump to Rs 2.04 lakh crore. Another strong indicator is the number of UPI transactions, which reportedly stood at 2,407 crore valued at Rs 29.37 lakh crore. UPI has made life easier for everybody, and now several neighbouring countries are tying up with India to adopt similar payment systems.
These numbers clearly reinforce the belief that India is an idea whose time has come. GDP is expanding, digital transactions are surging and tax collections are growing.
The statistics suggest good tidings. So, what could spoil the party?
To start with, the stock market. It has disappointed investors. On 14 October 2026, the Sensex stood at 72,781.89 points, reflecting a decline of approximately 11.89% over the preceding 12 months. However, one potential trigger that could give the market a big fillip is speculation that the Long-Term Capital Gains (LTCG) tax may be abolished.
Equally worrying is the continued selling by Foreign Institutional Investors (FIIs). During the calendar year up to October 2026, FIIs reportedly sold Indian equities worth over Rs 3.04 lakh crore. One reason for their exit is the strong dollar and elevated yields on U.S. bonds.
High crude oil prices are also putting pressure on India's import bill, threatening the macroeconomic balance. The prospect of higher inflation and a widening import bill has added to investor concerns. FIIs are also reallocating capital towards technology- and AI-driven markets in North Asia.
The monsoon has been 12.6% below the long-period average of 868.6 mm. It is reportedly the weakest monsoon since 2015, heavily impacted by El Niño conditions.
A poor monsoon is bound to push up food inflation. Prices of key vegetables and essential commodities, particularly onions, have risen sharply. Consumer Price Index (CPI) inflation, or headline inflation, rose to 5.54% in September 2026 from 4.82% in August. This spike is worrying the government.
Newspaper reports suggest that FMCG companies, two-wheeler manufacturers and tractor and farm equipment makers are witnessing a moderation or uneven recovery in rural purchasing power and sales growth.
Yet, none of these issues can, by any stretch of the imagination, derail the India growth story. For example, the country's Foreign Direct Investment (FDI) inflows reportedly jumped 17% to reach $95 billion in FY2025–26. Simply put, this suggests that the world continues to view India favourably.
To my mind, the encouraging statistics outweigh the depressing numbers. In other words, India's economic success should eventually translate into prosperity for ordinary Indians. It will take time, though.
There are, however, a couple of concerns.
India may be growing at 7–8%, but is it creating enough quality jobs? Look at youth unemployment, educated unemployment, real wages and the rise of gig employment. The overall unemployment rate remained steady at around 5% in September. In simple terms, this means that roughly five out of every 100 people in the labour force were unemployed.
To a large extent, the government has been doing much of the heavy lifting, spending heavily on infrastructure. But one does not see the same level of commitment from India's private sector in terms of expansion, diversification or acquisitions. Why are Indian companies shying away from investment when even multilateral institutions are optimistic about India's growth prospects?
What about small businesses, which are important employment generators? Are they growing profitably? Over the period spanning 2025 and 2026, roughly 420–440 SME companies were reportedly listed on the BSE SME and NSE Emerge platforms. But does the growing number of listings necessarily reflect the health of the broader small-business sector?
Premium cars, expensive homes, luxury holidays and high-end consumer products may be doing well. But what about entry-level cars, motorcycles, affordable housing and mass-market FMCG products? Is India witnessing broad-based prosperity or prosperity concentrated among higher-income households?
Various reports point to a stark reality. Research suggests that India is experiencing a consumption dichotomy, often described as a K-shaped recovery, where prosperity is disproportionately concentrated among higher-income households.
While the top 4% of earners are reportedly driving an unprecedented premiumisation wave, demand for entry-level cars has declined by 16%. Affordable housing, mass-market FMCG products and two-wheelers continue to witness sluggish or uneven demand.
There is a difference between a country becoming rich and its people becoming prosperous.
India can become the world's third-largest economy without necessarily becoming the world's third-most-prosperous society. The size of the economy matters, but so do per capita income, employment, purchasing power and quality of life.
India may well be an idea whose time has come. The tailwinds of demography, digitalisation, entrepreneurship and domestic demand are powerful. But the headwinds of inflation, unemployment, global uncertainty and unequal prosperity cannot be wished away.
The real test is not merely how fast India's GDP grows, but how many Indians participate in that growth.
Finally, there may be little need for crystal-ball gazing about India's future if one goes by the optimism of Canadian billionaire Prem Watsa, whose investment group has reportedly committed $5.6 billion to acquire a 60.72% stake in IDBI Bank.
Watsa told The Economic Times, his “...bet on IDBI Bank is backed by the conviction that India is in the midst of a sustained economic book that will continue over the next decade.”
May his tribe increase.