Parachute’s 60% Market Share: Why Marico Wants Less Commodity Risk
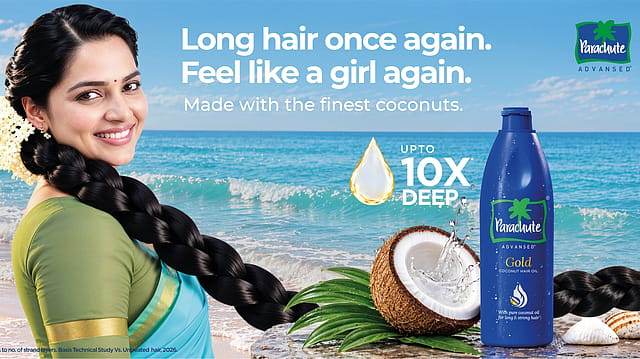
Parachute has reached a new market-share high. Marico still wants a business less exposed to commodity prices.
Its Q2FY27 disclosures put the Parachute Rigids franchise at approximately 60% volume share within coconut oil, measured over the year to September. Quarterly volumes grew 13%, the strongest performance in 22 quarters. Revenue growth was about 1%.
That gap captures an important feature of the business. Marico says earlier price reductions passed some of the benefit of easing copra costs to consumers. Copra, the dried coconut kernel used to produce coconut oil, remains a major influence on the franchise.
A powerful brand can help retain consumers through those changes. Its quarterly sales and margins still respond to the price of the ingredient inside the bottle.
The Era of Forever Wars
30 Oct 2026 - Vol 05 | Issue 44
Coping with an explosive Middle East
Marico’s ambition to reduce commodity exposure, therefore, deserves attention precisely when Parachute is doing well. The strategy asks whether the company can use strength in its established franchises to build a more resilient earnings mix.
Leadership has several jobs
Category leadership gives Marico meaningful advantages. It can support retailer acceptance, sourcing scale and consumer confidence. Those capabilities can help a company respond to both rising and falling costs.
During this quarter, price reductions and strong volume growth coexisted with a further gain in market share. That supports management’s argument that the franchise remains competitive.
The financial interpretation needs care. Higher volumes indicate more product sold; modest revenue growth also reflects changes in the amount realised from that product.
A consumer company managing deflation has choices about prices, pack sizes, promotion and the pace at which it passes on cost relief. Each affects demand, margins and the relationship with the trade.
Parachute’s performance suggests that Marico has managed this phase effectively. The harder assessment is how consistently the wider company can grow earnings when the commodity direction changes again.
Follow the gross-margin gain
The consolidated results show how much room the quarter provided.
Revenue rose 13% to ₹3,897 crore. EBITDA increased 27% to ₹709 crore, while the reported EBITDA margin rose from 16.2% to 18.2%.
Gross margin expanded by approximately six percentage points. Marico attributes the improvement to softer copra prices and a favourable portfolio mix.
A substantial part of that room was reinvested or absorbed by other operating expenses.
Advertising and sales promotion rose to ₹451 crore from ₹313 crore. As a proportion of revenue, it increased from 9.1% to 11.6%. Personnel and other expenses also took a higher share of sales.
The result was a two-percentage-point expansion in EBITDA margin.
This is a useful explanation of what management is doing with a favourable quarter. Marico is strengthening its current profitability while increasing expenditure behind the business it wants to build.
The subsequent return on that spending will help determine how much of today’s improvement survives less helpful input costs.
What the portfolio target actually means
Marico’s presentation shows premium and digital categories increasing from 27% of its global portfolio in FY20 to 37% in FY26. It targets 50% by FY30. The slide explicitly links that shift to reducing exposure to commodity-linked categories.
The company is also expanding foods and premium personal care in India, while increasing the role of beauty and personal-care categories internationally.
These are portfolio proportions. A declining share for commodity-linked categories can coexist with growth in their absolute sales if the rest of the business expands faster.
That distinction is central to understanding the strategy. Parachute remains a source of earnings, distribution strength and consumer relationships. Marico is seeking additional businesses that can contribute a larger part of future growth.
Its established franchises must continue to perform while those newer businesses absorb investment. Diversification therefore adds an execution requirement alongside the protection it may eventually provide.
Saffola shows a different choice
Within the same quarter, Saffola edible oils recorded 6% revenue growth and a high-single-digit volume decline.
Marico attributes the decline to a deliberate reset involving reduced supply of low-margin variants. It says the premium range, led by cold-pressed oils, grew faster than the overall portfolio.
That illustrates a different way of managing the balance between sales and profitability. A company can accept lower volumes in parts of its range while trying to improve what it earns from the business.
The success of that choice depends on the contribution retained from the products it continues to sell. Revenue growth alone cannot settle the question, and lower volume alone cannot establish that the strategy has failed.
For shareholders, the relevant progression is from management’s portfolio choices to sustained operating profit and cash generation.
The global search for a better mix
Unilever offers a useful global comparison, although its portfolio decisions follow a different route.
Its latest quarterly statement describes the proposed combination of its Foods business with McCormick as part of becoming a more focused home and personal-care company. Completion remains subject to approvals and other conditions.
Marico is building a larger foods business as part of its own diversification.
The differing choices show why category labels provide an incomplete investment argument. A company’s capabilities, competitive position and expected returns matter when it decides what belongs in its portfolio.
Unilever’s Q3 results also show continuing price increases to offset higher commodity costs. Moving into personal care does not remove the need to manage ingredients, packaging and affordability. Unilever
For Marico, the realistic ambition is lower sensitivity to particular commodity cycles, supported by a broader range of profitable businesses. Every new category will retain costs and risks of its own.
Premium products require premium execution
A more differentiated product may command a better price. The company must then sustain the reasons consumers pay it.
Product development, advertising, channel support and competition can consume part of the apparent advantage. Acquired brands also carry the financial hurdle created by their purchase price.
Marico’s target for digital-first businesses to achieve double-digit EBITDA margins by the FY27 exit is therefore an important companion to its revenue ambitions.
Its international plans add another dimension. Premium categories represented approximately 30% of international revenue in FY26, with a target of around 40% by FY30. Management also wants a greater contribution from markets beyond Bangladesh.
This creates several potential sources of resilience, but each must be earned through local execution. A broader portfolio becomes more useful when its businesses generate dependable returns under different conditions.
The test comes after the tailwind
Marico’s results commentary describes its evolution into a business with “a proven ability to deliver strong growth across commodity cycles”, in Gupta’s words.
The latest quarter offers encouraging evidence. Parachute gained share, India delivered double-digit volume growth, and the company increased brand investment while expanding operating margins.
The next assessment should examine how much progress comes from repeatable improvements: distribution productivity, stronger product mix and increasingly profitable newer businesses.
Those are capabilities that can continue contributing when coconut prices become less favourable.
Parachute’s 60% share explains the strength Marico brings to that task. The portfolio plan explains why management believes the task remains necessary. Leading a category and building a less volatile company are separate achievements.