Gold Could Hit $5,000; Copper Faces a 16-Year Wait for New Mines: Reports
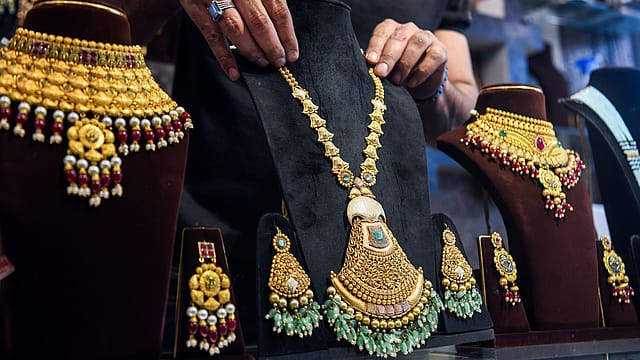
Gold could trade as high as $5,000 an ounce over the next two years, while copper faces persistent supply constraints as new mines take more than 16 years to reach production, according to separate reports by NDB Wealth Management and Goldman Sachs Research.
The reports point to different pressures supporting the two metals: sustained central bank and Asian investor demand for gold, and the difficulty of bringing additional copper supply to market.
GOLD’S CHANGING DRIVERS
NDB Wealth’s base-case scenario sees gold trading between $4,200 and $5,000 an ounce over the next 12–24 months. The firm assigned that scenario a 50 per cent probability.
Gold was quoted at $4,118.91 an ounce in the report, down 0.14 per cent at the time of filing.
Losing Memory
16 Oct 2026 - Vol 05 | Issue 42
The making of a medical and social emergency
The firm argued that central bank purchases and Asian investment were reducing the dominance of traditional price drivers such as US interest rates and the dollar.
“Gold has stopped trading off the Fed,” the report said, noting that the metal had remained resilient despite higher US rates and a firmer dollar.
According to the report, central banks bought 289 tonnes of gold in the second quarter of 2026. Asian gold funds attracted net inflows of nearly 70 tonnes in the first half, their strongest first-half performance on record.
North American gold funds, by contrast, recorded outflows of around 61 tonnes during the same period.
RESERVE DIVERSIFICATION SUPPORTS DEMAND
NDB Wealth said central banks were buying gold primarily to diversify reserves and reduce dependence on the US dollar, rather than to capture short-term price gains.
The report cited a World Gold Council projection of around 850 tonnes of central bank purchases in 2026, compared with 863 tonnes in 2025.
Supply growth could remain modest. Global mine production is forecast to increase 2.4 per cent to 3,907 tonnes in 2026, with mining costs and lengthy project development limiting the industry’s response to higher prices.
The outlook remains conditional. NDB Wealth identified lasting peace in the Gulf and easing inflation among potential downward pressures, while concerns about US government finances and Federal Reserve independence could support further gains.
COPPER’S LONG SUPPLY TIMELINE
For copper, Goldman Sachs identified a longer-term obstacle: new mines take a median of more than 16 years from discovery to first production.
With output from existing mines expected to begin declining from 2030, the report argued that higher prices alone would struggle to generate substantial additional supply within a typical investment horizon.
“Copper’s supply constraint is structural, not cyclical,” Goldman Sachs said.
Major discoveries have declined since the 1990s, while falling ore grades, particularly in South America, mean miners must process more material to produce the same quantity of copper. Increasingly remote projects also face higher construction and operating costs.
COSTS RISE AS PROJECTS ADVANCE
Goldman Sachs estimated that average capital intensity increases by around 50 per cent between pre-feasibility studies and production, rising from $10,600 to $15,900 per tonne of annual production capacity.
Its capital-cost estimates for projects covered in the report were 25–90 per cent higher than company studies.
The firm assessed a group of growth projects that could collectively add approximately one million tonnes of annual copper production by late 2035 and around $20 billion in net asset value.
Those additions depend on investment decisions, execution and control over costs and delays. Earlier-stage projects received larger valuation discounts to reflect uncertainty over their development timelines and recoverable reserves.
Goldman Sachs said these constraints could increase the value investors place on established producers and credible expansion projects. Its report did not specify a copper price target in the material provided.
With inputs from ANI