What Happens to the Food Business When Customers Want to Eat Less?
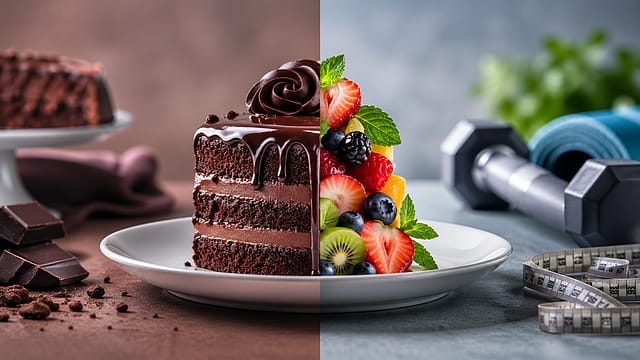
When Conagra introduced a “GLP-1 friendly” badge on 26 Healthy Choice meals, it made an important disclosure: the food itself had not changed.
The company was identifying existing products for a newly recognisable customer. Announced in December 2024 for rollout the following month, the badge highlighted meals with protein, fibre and smaller portions.
The distinction captures the emerging food-business response to appetite-suppressing medication. Some companies are developing products. Others are repositioning what they already sell. Both are pursuing customers whose food requirements may be changing.
The commercial question is how much additional revenue can be earned from people who want to consume less.
Zeroing In on ECI
09 Oct 2026 - Vol 05 | Issue 41
Constitutional legitimacy versus political opportunism
For manufacturers and restaurants accustomed to increasing purchase frequency, encouraging extra items or selling larger quantities, that is a significant adjustment. It also creates an opening for businesses offering convenience, appropriate portions and clearly communicated nutrition.
Whether those benefits support durable demand remains the test.
THE SPENDING CHANGE IS MEASURABLE
Research published in the Journal of Marketing Research provides evidence that changing appetites can affect purchasing.
Sylvia Hristakeva, Jūra Liaukonytė and Leo Feler linked reported medication adoption to US household transaction records. Within six months, households with at least one GLP-1 user reduced grocery spending by an average of 5.3%. Spending at fast-food chains, coffee shops and other limited-service restaurants fell 8%.
The changes were uneven. Savoury-snack spending declined 10.1%, while a small group of categories, led by yoghurt, showed directionally positive movements.
These are household spending measures, rather than direct measurements of food intake. As Cornell’s account of the research notes, medication effects cannot be fully separated from accompanying lifestyle changes.
Nevertheless, the findings challenge a comforting industry assumption: that lower spending on some foods will simply reappear elsewhere in the food basket.
New products must compete for expenditure within a household that may be spending less overall.
SELLING VALUE IN A SMALLER SERVING
Nestlé took a different route from Conagra, introducing Vital Pursuit as a dedicated US range aimed at GLP-1 users and other weight-management consumers. Its proposition combines portion-aligned meals with protein, fibre and nutrients.
Smoothie King also introduced a GLP-1 Support Menu, emphasising protein, fibre and no added sugar.
These are company-defined product propositions. Their commercial success depends on taste, price, convenience and repeat purchasing.
A smaller serving can reduce ingredient consumption, but other costs do not shrink proportionately. Packaging, distribution and customer acquisition still need paying for. Adding ingredients or developing a more complex formulation may increase costs.
The opportunity therefore involves earning sufficient value from each purchase while serving a customer who may buy fewer quantities.
That requires a reason to choose the product beyond its association with a medication. A convenient meal with transparent nutrition has a practical proposition. An expensive badge on an otherwise undifferentiated product has a harder case to make.
INDIA’S PLATE IS NOT ITS GROCERY BASKET
Indian evidence introduces a particularly useful complication.
IFF’s August 2026 report, Inside the India GLP-1 Consumer Journey, examined users in Delhi, Mumbai and Bengaluru. Participants reported smaller portions and greater attention to food information: 74% said they read labels more carefully after starting medication.
Yet household purchasing continued across familiar categories. Among respondents, 78% still bought biscuits for their households, 71% bought packaged sweets and full-fat dairy products, and 63% bought fried snacks.
These figures indicate continued purchasing, rather than unchanged spending or quantities. The study is an early consumer-insights exercise in three cities, not a national estimate.
Its central implication is still important: an individual’s reduced appetite need not translate directly into the disappearance of familiar household purchases.
For Indian brands, this creates several possible responses. Individual packs may become more relevant alongside family formats. Products may need to serve different preferences within the same household. Changes in personal consumption could influence the mix of purchases before materially reducing the entire basket.
US findings supply a valuable warning about demand. They do not establish the scale or timing of an equivalent Indian shift.
THE OCCASION STILL HAS VALUE
Food is also a social purchase.
IFF found that 64% of surveyed users experienced discomfort during social eating at least occasionally. Its research suggests people still wanted to participate in familiar occasions while adapting how much they ate.
For restaurants, that points towards a service opportunity: make smaller appetites easier to accommodate.
Flexible portions, clear descriptions and dishes that work within a shared meal could help retain customers. The business benefit would come from preserving a visit that might otherwise be avoided.
But pricing requires care. Customers may expect a smaller portion to cost less, while restaurants continue to incur staffing, occupancy and service expenses.
The task is to design a satisfying purchase whose value is understandable. Automatically presenting less food as a premium experience risks confusing the customer’s requirement with the operator’s margin objective.
THE STARTUP OPENING—AND ITS LIMIT
Investors are examining the surrounding market.
In an October interview with AgFunderNews, Peakbridge founding general partner Erich Sieber identified opportunities in evidence-backed functional ingredients and services supporting GLP-1 users. His argument places nutrition within a wider system of products, advice and ongoing support.
For startups, specialisation can create an opening. Established companies have distribution and manufacturing scale; smaller businesses may respond to particular tastes, formats or service requirements.
Yet this also makes market definition important. A protein product sold to a broad wellness audience cannot attribute all its demand to GLP-1 adoption. A launch does not establish repeat purchases. A nutrition claim requires evidence proportionate to what it promises.
The strongest businesses will need to demonstrate what customers actually choose, how often they return and whether the product remains viable after distribution and acquisition costs.
APPETITE IS A MOVING TARGET
The US research offers another caution: households discontinuing medication moved back towards their previous grocery-spending patterns.
That makes permanence a risky assumption.
A business built around changing appetites must remain useful across changing routines. Products appealing through taste, convenience and credible nutrition may have a broader base than those dependent on a narrowly defined treatment identity.
For India, the opportunity is to investigate these requirements without assuming that the entire food economy is about to contract.
Some customers may consume less. Families may keep buying familiar foods. Social occasions may remain important. The commercial advantage will belong to businesses that understand those differences—and offer something worth purchasing within them.