Silicon Valley Wants the Work. Can India Keep the Business?
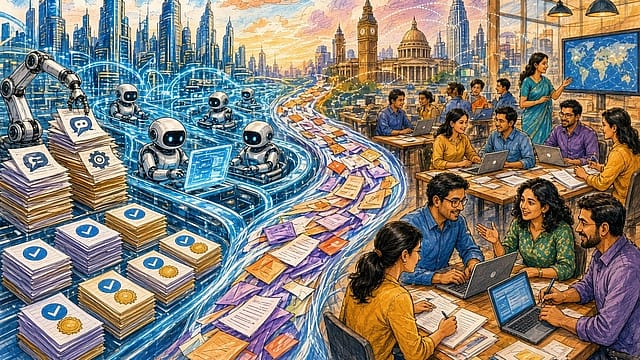
Crosby sells a familiar service through an unfamiliar operating model.
The American law firm reviews commercial contracts at fixed rates per document. AI agents research, analyse and draft; human attorneys review the work and manage the agents. The company says it carries malpractice insurance and takes responsibility for delivery.
The customer buys completed legal work. Behind that purchase sits a combination of software, professional judgment and accountability.
That arrangement captures a consequential ambition emerging in venture capital: AI companies competing for the money businesses spend getting work done.
For India, whose technology-services industry built global scale by delivering work for overseas clients, this creates a different competitive question. What happens when a customer can buy a completed task from a specialist whose delivery system requires progressively less human effort?
Zeroing In on ECI
09 Oct 2026 - Vol 05 | Issue 41
Constitutional legitimacy versus political opportunism
The answer will depend as much on contracts and operating economics as on model capabilities.
THE BUDGET BEYOND SOFTWARE
Bessemer Venture Partners frames the opportunity as “AI-native services”. Its investment framework asks whether machines can perform enough of the underlying work to improve delivery economics—and whether the supplier can retain those gains rather than surrender them through competition.
The distinction matters.
A tool that helps an employee process a claim competes for a software budget. A supplier that processes the claim can potentially compete for a wider combination of labour, technology and outsourcing expenditure.
Taking on the work also changes the obligation. The supplier must handle incomplete information, exceptions, integrations and quality control. It needs a dependable route from a customer’s request to an acceptable result.
An impressive demonstration establishes only part of that capability.
PAYMENT FOLLOWS PERFORMANCE
Customer-service startup Sierra illustrates another version of the approach. It describes pricing linked to agreed outcomes, such as resolving a query or retaining a customer. Unresolved or escalated conversations generally do not attract a charge, although arrangements can include blended pricing.
This shifts some performance risk towards the supplier.
It also makes the definition of success commercially important. A conversation ending is different from a problem being resolved. A cancellation prevented today may return tomorrow. Supplier and customer need rules for deciding when the work qualifies for payment.
The economic promise is straightforward: if the fee remains attractive while the cost of successful delivery falls, the supplier can improve margins.
But automation does not guarantee that outcome. Customers can negotiate lower prices. Competitors can offer similar capabilities. Difficult cases can consume disproportionate resources.
The important unit is the cost of an accepted result, including the failures and human interventions required to produce it.
INDIA ALREADY KNOWS THE CUSTOMER
Indian outsourcing companies have substantial assets in this contest: enterprise relationships, industry expertise, operating experience and familiarity with complicated systems.
They also have experience with fixed-price projects, managed services and contractual performance obligations. Outcome-oriented delivery is not a Silicon Valley invention.
What AI could change is the amount of labour required behind the contract.
Under an hourly arrangement, completing work faster can reduce billable effort. Under a fixed-price arrangement, the provider may initially retain productivity gains. At renewal, the customer may demand a share through lower prices.
That creates a negotiation over who benefits from automation.
The same technology can therefore support new business, improve delivery margins and put pressure on existing revenue. Those effects can occur simultaneously.
THE INCUMBENTS ARE RESPONDING
TCS’s latest results provide evidence that established providers remain active participants.
For the September quarter, the company reported an annualised AI revenue run rate of $3.1 billion, alongside quarterly group revenue of $7.64 billion and a 24% operating margin. Its announced Best Buy agreement involves transforming the retailer’s Indian global capability centre into an AI capability centre.
The run-rate figure is not annual revenue already earned. It nevertheless demonstrates commercial activity beyond an intention to adopt AI.
The larger question is how that activity changes the business: revenue per employee, delivery costs, customer savings and the durability of earnings.
Large providers can spread investment across clients and combine technical work with broader transformation programmes. Their challenge is to reorganise delivery and commercial incentives while protecting existing relationships.
Startups face the inverse problem. They can design an operation around AI from the beginning, but must earn trust, access customer systems and demonstrate reliability.
A SPECIALIST OPENING
For Indian founders, a promising route lies in narrowly defined, difficult workflows.
Graph AI offers an illustrative case. According to a Bessemer case study, the company began in services before developing a specialised platform for pharmacovigilance, the collection and reporting of drug-safety information. Its founders include veterans of established technology-services businesses.
This is an investor-published account, rather than independent proof of the company’s economics. Its significance is the development path: experience gained in service delivery can help identify a repeatable problem around which to build a product.
Aivar similarly markets an approach spanning AI development and managed operations, supported by reusable accelerators.
These examples suggest that India’s service capabilities could supply the foundations for new competitors. The opportunity involves converting experience into repeatable systems that serve additional customers with less incremental effort.
That requires more than assembling a team around readily available models. Industry knowledge, integration, evaluation and operational judgment must become capabilities competitors cannot quickly reproduce.
THE SAVINGS CAN LEAVE THE SUPPLIER
The strongest caution concerns value capture.
If several companies can automate the same task, falling delivery costs may translate into lower customer prices. The market can become more efficient without producing exceptional supplier profits.
Specialists need reasons customers continue choosing them: dependable execution, difficult integrations, accumulated knowledge or the cost of changing a trusted process.
Human involvement can strengthen that proposition. Crosby’s attorneys, for example, are part of the responsibility it sells. Their presence also means delivery costs must be included when assessing the model.
A business does not acquire software economics simply by describing itself as AI-native.
THE ADVANTAGE TO BUILD NEXT
India’s opportunity is to compete on the cost and quality of completed work, with technology reducing the effort required to deliver it.
For incumbents, that means capturing new mandates while redesigning existing operations. For startups, it means proving that a specialised system can repeatedly fulfil a customer obligation at viable margins.
Neither position guarantees success. The established provider may adapt faster than expected; the specialist may discover that exceptions overwhelm its automation.
The decisive evidence will be practical: accepted outputs, repeat contracts, falling delivery costs and earnings that survive renewal negotiations.
Silicon Valley’s ambition is expanding into services. India’s response will be strongest where its companies combine knowledge of the work with better ways of completing it.