Taking Stock of India: Over-regulation weighs down the equity market
Stock markets have an inverse relationship with economic growth. While India’s GDP has grown at nearly 8 per cent annually, the BSE Sensex has fallen from 85,000 to 71,000 in a matter of months. The Nifty 50 is lower in October 2026 (22,000) than it was in October 2024 (24,000).
The cause: wars, trade, oil, drought, and the rupee.
Why haven’t the same negative factors affected GDP growth, industrial production, consumption, private investment, and exports that are poised to breach for the first time the $1 trillion milestone in 2026-27?
Stocks react to short-term cues. The economy takes a broader, long-term view. Wealth manager Somnath Mukherjee explained it well in a recent Times of India oped: “Public equity markets capture a narrow, often non-representative slice of the economy—while GDP includes government spending, agriculture, informal sectors and unlisted SMEs that never touch an exchange.”
China is the best example of the equity-GDP disconnect. Between the 1990s and 2010s, Chinese nominal GDP grew during some years at 15 per cent (including the inflation deflator). For example, China’s compounded annual growth rate (CAGR) in the five-year period 2009-14 was 14.5 per cent. It enabled Chinese GDP to leap from $5.19 trillion in 2009 to $10.68 trillion in 2014. That didn’t enthuse the Chinese stock market which ambled along at 7 per cent a year.
Stock market traders want profits and blame the government for making the problem worse. For instance, STT (Securities Transaction Tax) was introduced in the 2004-05 Union Budget by then Finance Minister P Chidambaram. It collected a mere `57,522 crore for the treasury in 2025-26 but cut the thin margins of day traders as well as those who deal in derivatives. SEBI, in particular, has been an inconsistent regulator. It has enacted strict rules for foreign portfolio investors (FPIs) in derivatives trading with onerous compliance demands.
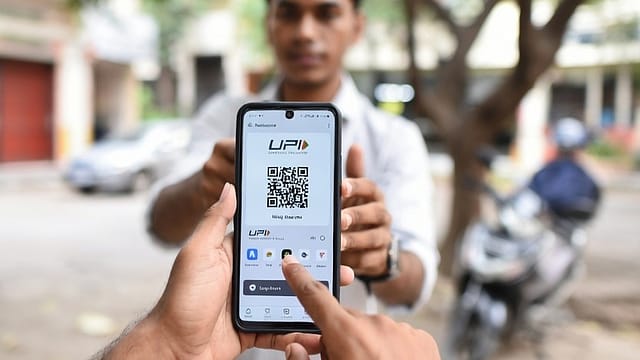
Over-regulation has eroded support for the Modi government among a small but influential vote bank: MSME owners, traders and vendors. The 0.4 per cent MDR charge on specific UPI transactions from October 15 has upset vendors who say they will pass on the cost to buyers. The `2,000 limit, though usable in bits through the day without attracting 0.4 per cent MDR, is however not a panacea. The finance ministry says only 4 per cent of UPI users will attract the 0.4 per cent MDR charge. The rest, 96 per cent, will be exempt. This is misleading. Over 67 per cent of all UPI transactions (by value, not by number of users) will attract MDR.
For the BJP-led NDA, trader unhappiness over SEBI’s over-regulation is bad news. Millions of small vendors, from fruit-sellers to grocery stores, are unhappy with the changes made in UPI. The Modi government faces a make-or-break test in February 2027 with the first of seven crucial state Assembly elections through 2027, kicking off with Uttar Pradesh (UP). The year ends with the Gujarat election. In between, lie Punjab, Goa, Himachal, Uttarkhand, and Manipur.
In the 2024 Lok Sabha election, it was UP that prevented BJP from winning a majority in Parliament on its own. It had won 71 parliamentary seats from UP in the 2014 Lok Sabha poll and 62 seats in 2019, but was reduced to 33 seats in 2024. BJP had needed to win 62-71 seats, as in 2019 and 2014, to cross 272 seats in 2024. It failed, ending with 240 seats. The 2027 UP Assembly election will be a litmus test for the 2029 Lok Sabha polls. Without a big chunk of UP’s 80 seats, BJP will struggle in 2029 to come close to 272 seats.
Modi knows that the next 30 months are among the most crucial in his prime ministership. Pressure on him is building at different levels simultaneously: the two wars, the frayed relationship with the US, the drought caused by El Niño, oil prices over $100 a barrel, and the political fallout over SIR. Sections of the electorate are concerned about rising corruption at state and municipal levels and slothful city infrastructure even as national-level expressways and high-speed rail are transforming logistics across the country.
For stock market traders, none of this matters. They want regulations simplified, STT removed and equities back to last year’s levels. The wait could test their patience.