Karta AI Raises $3 Million: Can Voice AI Fix India’s Bank Helplines?
A borrower calling a lender about a delayed disbursal may also need an account statement and an explanation of what happens next. From the customer’s perspective, it is one problem. Within the institution, the answers may sit in different systems and teams.
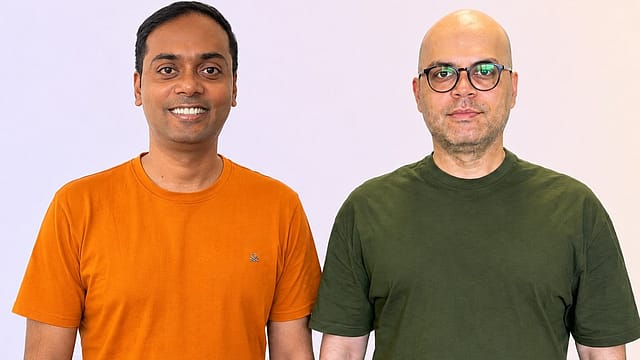
Karta AI wants a voice agent to handle that conversation and complete the required work. The Bengaluru startup has raised $3 million in seed funding, led by PeerCapital and Cedar Hill Capital, to expand its platform for inbound customer operations in financial services. Wyser VC, CDM Capital and Seedstars also participated.
Founded in 2024 by Vijaypal Singh and Abhishek Kushwaha, Karta is targeting incoming calls involving several requests, connections to enterprise systems and actions that go beyond reciting information. The larger question is whether AI can lower the cost of bank customer service while reducing the effort customers expend to get something done.
Losing Memory
16 Oct 2026 - Vol 05 | Issue 42
The making of a medical and social emergency
WHAT DOES KARTA AI DO DIFFERENTLY?
An outbound payment reminder begins with a known purpose. An incoming customer could ask about an unexplained charge, change direction midway and add a second request. Understanding the conversation is only part of the job: the agent must retrieve the right information, follow the institution’s rules and recognise when a person needs to intervene.
Karta describes its approach as multi-intent voice AI. Its predictive context engine draws on previous human and automated interactions to inform subsequent responses and workflows. The proposed advantage lies in using that context to complete connected tasks. “We built Karta AI to resolve the hard calls, the ones that need several systems and more than one answer, and to bring in a human only when it matters,” says Vijaypal Singh, co-founder and CEO.
That is a concrete proposition. Establishing an advantage requires evidence that the system completes more difficult requests reliably, integrates economically and improves customer experience across repeated use.
HOW MUCH OF THE CUSTOMER’S PROBLEM IS RESOLVED?
Karta says it handles around two million customer conversations monthly across more than 25 languages. At one home-loan company, it claims approximately 70% end-to-end resolution of borrower queries and roughly 50% lower cost per query. The examples include disbursal status, account statements, foreclosure statements and property-document release.
The scope of each task matters. Explaining how to obtain a foreclosure statement differs from generating and delivering the correct document. Providing an update on property documents differs from completing their release. Both information and execution can be valuable; the claimed resolution rate needs to identify what was completed.
The figures supplied by Karta do not identify the lender or establish whether the denominator covers all incoming queries or a selected set. They also do not show how often customers return with the same unresolved issue. These are company claims whose definitions remain important to assessing the outcome. Karta separately reports 25% more conversions than human agents in a payments-company retention use case. That measures a different objective.
WHAT GLOBAL VOICE AI DEPLOYMENTS SHOW
Experience abroad demonstrates an existing market for improving incoming financial-service calls.
In a published customer case, PolyAI describes helping Atos automate calls for a government-backed financial service. The system answered common questions and connected more complex queries to people. PolyAI reports a 30% reduction in calls reaching human agents, with capacity freed for more demanding work.
This is a vendor-published account with named Atos managers. It supports the commercial usefulness of automating part of the workload, while illustrating why percentages require care: fewer calls reaching an employee is a different measure from Karta’s claimed share of borrower queries resolved.
In the US, KeyPoint Credit Union selected interface.ai to improve round-the-clock support and reduce reliance on an outside provider for after-hours calls. Its operations executive described inconsistent outsourced service and fluctuating demand as problems. The vendor’s account documents the institution’s rationale and intended benefits, without supplying a verified final resolution rate.
These cases reveal several possible sources of value: availability, managing demand peaks, consistent answers and giving employees more time for difficult requests. Lower staffing expenditure is one part of the opportunity.
WHAT KLARNA’S AI EXPERIENCE ACTUALLY ESTABLISHES
Klarna offers a broader financial-services comparison, although its published evidence concerns customer-service chat rather than Karta’s voice proposition.
In a July 16, 2025 response to the US Securities and Exchange Commission, Klarna said its assistant handled 66% of customer-service chats in the twelve months ended March 31, 2025 and delivered approximately $39 million in savings during 2024. These were Klarna’s own reported measures.
The correspondence also addressed accounts suggesting that AI service quality had disappointed. Klarna disputed that interpretation, saying its chief executive’s remarks concerned improving human support. It described continued AI deployment alongside the option to reach a person.
That record complicates a simple story of automation being abandoned. It also shows that substantial automated volumes can coexist with investment in human assistance. The relevant question for Karta is how well the two forms of service work together, particularly when an automated interaction reaches its limit.
IS INBOUND BANKING AI A DISTINCTIVE MARKET POSITION?
Karta investor Sahil Anand of Cedar Hill Capital argues that incoming calls are harder than outbound interactions because their purpose is unpredictable and can involve several requests. That explains the investment rationale; it does not establish that Karta occupies an uncontested category.
India’s Gnani.ai already markets inbound support, retrieval of backend information and escalation to human teams. Internationally, interface.ai offers banking-specific voice agents and connections to core systems. These are competing product claims, not a comparative performance assessment.
Other fundraises show investment across related parts of this market. Desible.ai has raised ₹32 crore in a seed-plus round led by Prime Venture Partners. Navana.ai has secured ₹40 crore led by Ronnie Screwvala, backing its Indian-language voice technology. Rezolv has raised $12.5 million in a Series A led by Norwest for its lending-technology business.
These businesses span conversational workflows, speech infrastructure and collections; they should not be treated as identical competitors. Their presence raises the importance of demonstrating where Karta performs better.
Karta’s defensible advantage would therefore need to emerge from execution: integration quality, task accuracy, deployment time, accumulated operating knowledge and customer retention. A natural-sounding conversation alone would be a limited basis for differentiation.
WHAT MUST VOICE AI GET RIGHT IN INDIA?
Multilingual support could make bank helplines more accessible. Its usefulness depends on handling actual conversations, including changes between languages, interruptions and precise account information. A count of supported languages does not reveal performance across those conditions.
The bank’s systems also determine what the agent can accomplish. Correctly identifying a request will achieve little if the required document is unavailable or an exception awaits approval. An agent needs appropriate access, reliable information and clear limits on the actions it can take.
Human assistance becomes part of that design. A transfer should carry the customer’s explanation and completed verification forward, avoiding another round of questions. Sensitive or disputed cases may require judgment that the institution chooses to keep with its staff.
Existing human service has costs and inconsistencies too. Well-designed automation could improve availability and repeatability. Assessing it fairly requires comparison with the service customers actually receive, alongside scrutiny of new errors and obstacles.
CAN KARTA TURN LOWER SUPPORT COSTS INTO A BUSINESS?
Karta plans to use the funding to improve its platform and multilingual capabilities, expand financial-institution deployments, and grow engineering and commercial teams. It also intends to develop reusable industry capabilities and eventually enter international markets.
Reuse is financially important. A solution that needs extensive rebuilding for every institution can accumulate engineering and support costs. Common integrations and repeatable workflows could make subsequent deployments more economical. The available figures do not establish that trajectory or Karta’s margins.
For the buyer, the useful comparison includes software, telephony, integration, supervision, escalations and rework. A lower cost for an individual automated query may not capture the full cost of completing the customer’s request.
The clearest measure is cost per correctly completed request, checked against repeat contact and customer confirmation. That connects the bank’s financial objective with the outcome the caller needs.
Karta has identified a consequential part of financial services to automate. Its long-term value will depend on how often a customer can finish the call knowing the required work has actually been done.