Budget Blueprint: A simple formula can transform everyday money decisions
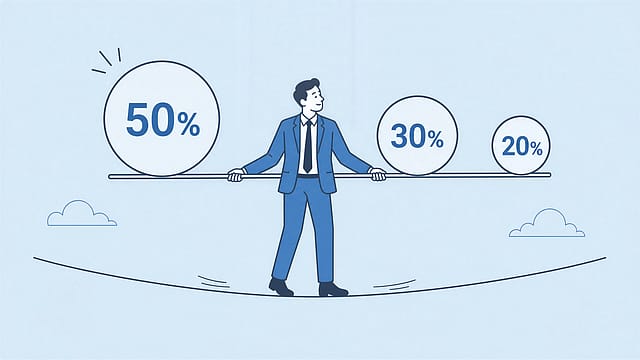
For many households, budgeting feels like a punishment: endless spreadsheets, complicated categories and difficult choices between present comforts and future goals. The 50/30/20 rule offers a simpler alternative. It divides take-home income into three broad buckets—needs, wants and savings—giving people a practical framework without requiring them to track every rupee.
The rule suggests allocating 50 per cent of after-tax income to needs. These are essential expenses such as rent or home-loan payments, groceries, utilities, healthcare, insurance, transport and minimum debt repayments. The objective is to ensure that basic living costs do not consume the entire pay cheque. Another 30 per cent can be directed towards wants—the expenses that make life more enjoyable but are not essential for survival. Eating out, entertainment, holidays, hobbies, shopping, streaming subscriptions and lifestyle upgrades belong here. This category is important because a sustainable budget should leave room for enjoyment rather than demand complete deprivation.
The remaining 20 per cent is meant for savings and financial goals. It can be used to build an emergency fund, invest for retirement, repay debt faster or save for a house, education or other milestones. For an Indian household, this bucket could include systematic investment plans, provident-fund contributions, fixed deposits or other suitable investments, depending on goals and risk appetite.
Consider a monthly take-home income of Rs 1 lakh. The framework would assign Rs 50,000 to needs, Rs 30,000 to wants and Rs 20,000 to savings or debt reduction. These are guidelines, not rigid commandments. Someone living in a high-rent city may need to devote more than half to essentials, while a young professional with limited obligations may save considerably more. The rule works best as a starting point. Review expenses regularly, separate needs from wants honestly and increase the savings share whenever income rises. Its real value lies not in perfect percentages, but in creating a conscious balance between living well today and remaining financially secure tomorrow.